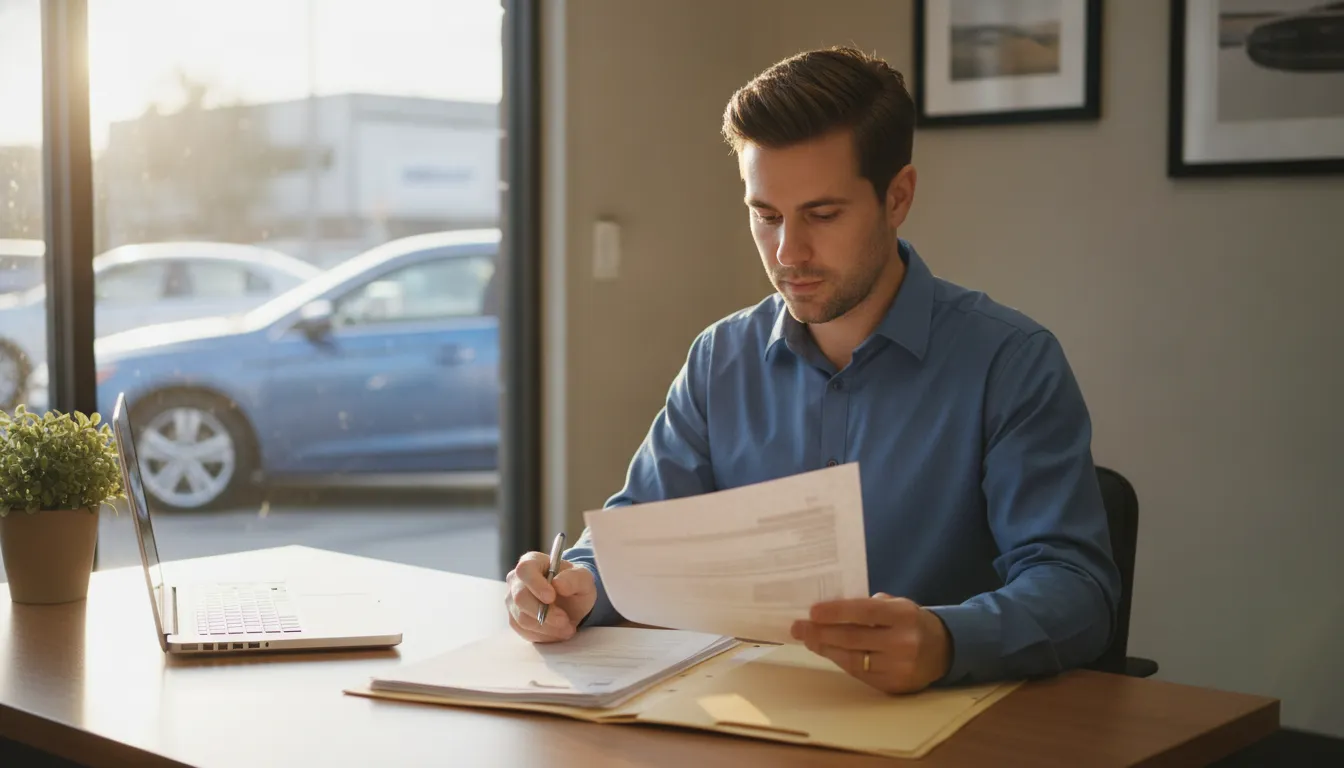
Applying for a used-car loan is easier to discuss when you have your details in front of you. Before you start, gather photo identification and proof of your Ontario address. Add recent pay stubs or other income records. Include any bank information a lender may request for pre-authorized payments. Reviewing your credit report can also help you catch errors and prepare to explain late payments, collections, or an insolvency in your own words.
For a bad credit car loan Ontario application, prepare accurate identification, address and income documents, review your credit report, and set a realistic vehicle budget. These steps do not guarantee approval, a rate, or a payment because terms depend on the applicant, lender, vehicle, and verification details.
You can get your credit report online for free through Equifax or TransUnion, and checking your own report does not affect your credit rating. With those basics ready, it becomes clearer what the application can and cannot establish about your borrowing options.
Start a financing application when your documents are ready. Applying does not guarantee approval, a rate, or a payment.
What a bad credit car loan in Ontario actually depends on
A challenged credit history is one part of a used-car financing application, not the whole decision. A lender may consider whether your income appears stable. It may also look at your debts, the vehicle, and how much you want to finance. The lender may also need to verify the information in your application before deciding whether to offer credit and on what terms.
That means two people with similar credit histories may not receive the same answer. The amount financed can change with the vehicle price, a trade-in, or a down payment, if either is available. The vehicle itself matters because its age, condition, and value can affect the lender’s assessment of the loan. Your budget matters too: a payment that looks manageable on its own still needs to fit alongside your existing obligations.
Verification is another practical part of the process. Be prepared to provide accurate information about your identity, address, employment, income, and current debts. A lender may ask for supporting documents, and the exact requirements can vary. Gathering your records before applying can make questions easier to answer. It does not guarantee approval or a particular rate, payment, or term.
Before you apply, review the vehicle price and the total amount you would need to borrow. Ask what information will be checked and whether a credit check is a soft inquiry or a full application. You can also read this guide to how car loans are structured in Canada for background on the parts of a financing agreement.
Search results for bad credit car loans in Ontario often lead with broad promises of help or approval. A more useful approach is to treat financing as an assessment of your full situation. Share complete, current information, compare the vehicle and loan amount with your budget, and avoid assuming that a credit label alone determines the outcome.
Check your credit report before you apply
Order your credit reports before you apply. Read them carefully. The Financial Consumer Agency of Canada says you can order a free credit report online from both Equifax and TransUnion. Checking your own report or score does not affect your credit rating. Equifax provides a free credit score everywhere in Canada, while TransUnion provides a free score to Ontario residents as part of Consumer Disclosure.
Review both reports because the information may not be identical. Check your name and address first. Then look for accounts that are not yours, late payments and their dates, collections, and any past insolvency.
If you see an error, follow the bureau’s process for reviewing the information and keep copies of your records. Do not assume that a dispute will raise your score or change a lender’s decision. The immediate benefit of checking is knowing what information may be reviewed and having time to identify anything that needs clarification.
You can also prepare a short, factual explanation for a lender if your report includes late payments, collections, or a past insolvency. Keep the explanation focused on the circumstances and what has changed since then. It is better to describe your situation clearly than to leave a lender guessing about an entry in the report.
Before consenting to a credit check at a dealership or with a lender, ask what type of inquiry it will be. Specifically, ask whether it is a soft inquiry for information or a full application that creates an inquiry on your report. Multiple applications in a short period can each create an inquiry, so make sure you understand what you are authorizing before you proceed. Any financing terms will depend on your application, the lender, the vehicle, and verification.
Documents worth gathering for an Ontario application
A few details ready can make the conversation more straightforward. The exact documents depend on the lender, your situation, and the vehicle. Treat this as a preparation checklist, not a list of universal requirements.
Prepare government photo identification. Set aside a current government-issued photo ID so your identity and application details can be verified. Check that your name is consistent across the documents you plan to provide. If your identification is expired or your personal information has recently changed, ask what updated documentation may be accepted before submitting an application.
Confirm your Ontario address. Gather a document that shows your current Ontario address, such as a recent statement or other official correspondence. A clear address record helps keep the application accurate. Ontario’s age of majority is 18 under the Age of Majority and Accountability Act, although a lender may still set its own applicant rules.
Collect recent income records. Recent pay stubs can be useful, and other income records may also help explain how you are paid. Keep the information readable and current. If regular pay stubs do not show your income, ask which records would document it. Do not assume one format fits every lender.
Have banking details available when requested. A lender may ask for bank details or a void cheque if pre-authorized payments are being arranged. Only provide those details through the requested secure process, and confirm the account information before authorizing anything.
Plan for proof of insurance. Proof of insurance is commonly needed before you can drive a financed vehicle away. Contact an insurer early enough to understand what information they need, then keep the proof accessible for the dealership and lender if requested.
Gathering these records does not guarantee approval or a particular rate, term, or payment. It simply gives you a clearer starting point and helps you answer verification questions without searching for documents at the last minute.
Set a vehicle budget before you talk numbers
Keep the vehicle price separate from the other costs that show up before you drive away. This comparison is a planning aid, not a quote.
| Cost to check | What to confirm |
|---|---|
| Vehicle price | Ask whether the advertised figure already includes dealer fees. |
| HST and licensing | These can sit outside the advertised price when the ad says so. |
| Insurance | Get a quote on the specific vehicle before you rely on a payment sketch. |
| Amount financed | A down payment or trade-in can lower it. Neither is guaranteed to be available. |
A useful budget starts with the vehicle you can live with, not with a payment someone else suggests. Look at how you will use the car on a normal week: commuting, family seats, winter driving, and parking. A smaller, simpler vehicle can be easier to insure and maintain than a larger one that stretches the amount you finance. You can match a vehicle to your daily use before you sit down with an application.
Separate the advertised price from the full cost of taking the vehicle home. In Ontario, harmonized sales tax and licensing can sit outside an advertised price when the ad says so. Insurance, fuel, and repairs are yours after that. Ask an insurer for a quote on the specific vehicle before you commit. The premium can change what you can put toward a loan.
If you want a ceiling while you look, compare used vehicles under $15,000 and decide which ones still leave room for tax, licensing, and insurance. A down payment or a trade-in can reduce the amount financed when you have one. Neither is required by this checklist, and neither guarantees an approval or a particular rate.
A payment calculator can help you see how price, term, and rate move together, but treat the result as a sketch. The calculator on the financing application page is marked for demonstration only. The rate and term are not guaranteed, and they are subject to change. Do not treat a calculator figure as the payment you will be offered. Any offer still depends on you, the lender, the vehicle, and the documents that get verified.
Know your protections when you buy from an Ontario dealer
A purchase from an OMVIC-registered Ontario dealer is covered by the Motor Vehicle Dealers Act. Before you sign anything, confirm that the dealer is registered with OMVIC. This is a separate check from comparing vehicles or arranging financing, and it helps you understand which protections apply to the transaction.
A private purchase is different. OMVIC does not assist with private sales, and a buyer cannot make a claim through the Motor Vehicle Dealers Compensation Fund for a private purchase. A vehicle advertised by an individual does not come with the same OMVIC support. A registered-dealer purchase is different.
Ontario also has all-in price advertising rules. If an advertisement shows a vehicle price, that price must include all fees and charges the dealer intends to collect. HST and licensing can be left out only when the advertisement clearly says they are extra. Ask questions if the advertised price and the amount on the paperwork do not appear to match. OMVIC explains more about buyer rights when purchasing from an Ontario dealer.
Before agreeing to a bad credit car loan in Ontario, ask for the full amount you would finance in writing. Review the vehicle price, fees, taxes, licensing, any trade-in credit or down payment, and the amount being financed. You should also read the vehicle-history disclosures carefully and ask about anything you do not understand. Keep copies of the advertisement and documents you receive.
Canada Auto Financing is not described here as OMVIC-registered. Confirm the dealer’s current registration yourself before proceeding, and do not rely on an advertised price alone to understand the final cost.
Questions to ask before you submit an application
Before you apply, understand what will be checked. Also understand what you are agreeing to. Clear questions can help you compare your options without assuming that an application guarantees approval or a particular loan term.
- Is this a soft inquiry or a full credit application? This helps you understand whether the lender or dealership is only discussing your options or checking your credit as part of a formal application. Multiple applications in a short period can each create an inquiry, so ask before you consent.
- Which lender would review my file? Knowing who may assess your application helps you understand where questions about the proposed terms should be directed.
- What documents will you need from me? Asking first helps you prepare the information requested for your situation without assuming that every lender requires the same documents.
- What fees are included in the amount financed? This lets you see whether the amount borrowed includes charges beyond the vehicle price and compare the full cost more accurately.
- What happens if I decide not to proceed? Understanding the next step before you apply helps you make an informed choice if the terms, vehicle, or total cost do not suit your budget.
- Will I see the full agreement before I sign? You should have an opportunity to review the agreement, including the amount financed, fees, rate, payment, and other terms, before making a final decision.
If you want to discuss your questions with the North York team, any offer will depend on the applicant, lender, vehicle, and verification.
Contact the North York team if you want to talk through a used-vehicle budget before you apply.
Frequently Asked Questions
What documents should I prepare before applying for a bad credit car loan in Ontario?
Gather government photo identification and proof of your Ontario address. Add recent income records. Include bank details or a void cheque if pre-authorized payments are requested. You may also need proof of insurance before driving a financed vehicle away. The exact documents depend on the lender and your application.
Should I check my credit report before applying for a car loan?
Yes. Reviewing your report can help you find account errors and prepare an accurate explanation for late payments, collections, or a past insolvency. The Financial Consumer Agency of Canada says you can obtain your credit report online for free from Equifax and TransUnion. Checking your own report does not affect your credit rating.
Can I get a car loan in Ontario with really bad credit?
Possibly, but there is no universal credit-score cutoff or guaranteed outcome. Lenders assess each application using information about the applicant, lender, vehicle, and verification. Bring complete, accurate documents and be prepared to discuss your current circumstances rather than relying on an approval promise.
Does applying for a car loan affect my credit score?
A full application can create a credit inquiry, and multiple applications in a short period can each create one. Before consenting, ask whether the check is a soft inquiry or a full application. The effect varies, so avoid assuming that every preliminary conversation will affect your credit.
Talk through your next step
When your documents and budget are in order, you can start an application. You can also ask a question first. Canada Auto Financing is a used-car dealership at 3675 Keele Street in North York. The team can walk through inventory and the application with you. Calling or applying does not mean you are approved, and it does not lock in a rate or a payment.
You can start a financing application or call 1-855-581-9598. Hours are by appointment.